A guide for parents and teachers · K–12
Financial literacy for kids: what to teach, and when.
Financial literacy for kids is the set of money skills a child can actually use at their age. For a five-year-old that means telling a need from a want and learning to wait. For a fifteen-year-old it means reading a paycheck and knowing what a credit card really costs. This guide covers when those skills form, what to teach at each age, and what you can do today.
Why start earlier than you think
Money habits start forming early. A University of Cambridge review for the UK's Money Advice Service found that the foundations underneath adult money behavior, like putting off a reward and planning ahead, take shape in early childhood, and that by about age seven a child can grasp what money is worth FL 201. The U.S. Consumer Financial Protection Bureau describes the same order: self-control first (ages 3 to 5), then money habits and norms (6 to 12), then knowledge and decision-making (13 to 21) FL 205.
It matters later, too. A study that followed 1,000 children to age 32 found that self-control in childhood predicted adult income, savings and debt, regardless of IQ or family background FL 204. And teaching works at young ages: in a randomized trial, fourth and fifth graders who had five money lessons knew more, some of their money habits and attitudes improved, and the gains were still there a year later FL 311.
The short version: state requirements start in high school, but the foundations of money habits form in the early grades. The early years fall to families and to the schools that choose to start sooner.
What to teach at each age
Four stages, each built on the one before. The "at home" ideas need no worksheet; the free worksheet for each stage is linked underneath.
Money is a tool, and choosing is the skill
What they can understand
Coins and bills have names. People earn money by working. Money spent on one thing can't be spent on another. Saving means waiting. Giving is a choice too.
At home
- At the store, ask "is that a need or a want?" Take either answer, then ask why.
- Keep savings in a clear jar. Coins a child can see are coins a child understands.
- Let a small goal take two or three weeks. The waiting is the lesson.
A plan before the money is spent
What they can understand
Different work pays differently. Prices can be compared, and ads are trying to change your mind. A budget is a plan made before spending. Money kept in the right place can grow. Taxes pay for things everyone uses.
At home
- Give an allowance that has to cover something real, so the budget has stakes.
- Compare two sizes of the same product by unit price. Let your child do the division.
- Show a savings statement with the interest line circled, however small.
The systems behind the money
What they can understand
A paycheck is smaller than the wage, and why. Credit is borrowing from your future self, and a credit score follows you. Stores are designed around impulse. Time multiplies money that's left alone, so starting early beats starting big.
At home
- Trace a real pay stub, yours or a made-up one, from gross to net.
- Explain one household bill: what it's for, when it's due, what happens if it's late.
- Run the compound interest calculator with their own numbers and let them change the years.
The decisions that start for real
What they can understand
What a career is worth over forty years. The true cost of borrowing, and how to build credit. Investing before 25: risk, return and index funds. Insurance. Paying for college or trade school, and a plan for the first year on your own.
At home
- Read one credit card offer out loud, all of it, fine print included.
- Open a college's net price calculator together. The sticker price isn't the price.
- Build the first month's budget of their adult life on paper: rent, phone, food, transport, and a line for what goes wrong.
The longer version, with the units behind each stage, is the free Money by Age guide. Teaching a class? Each stage has a complete free financial literacy lesson plan, ready to print.
Financial literacy activities for kids you can do today
You don’t need to be good with money yourself, or to plan a lesson. Each of these fits into something you already do with your child, and none of them is a lecture.
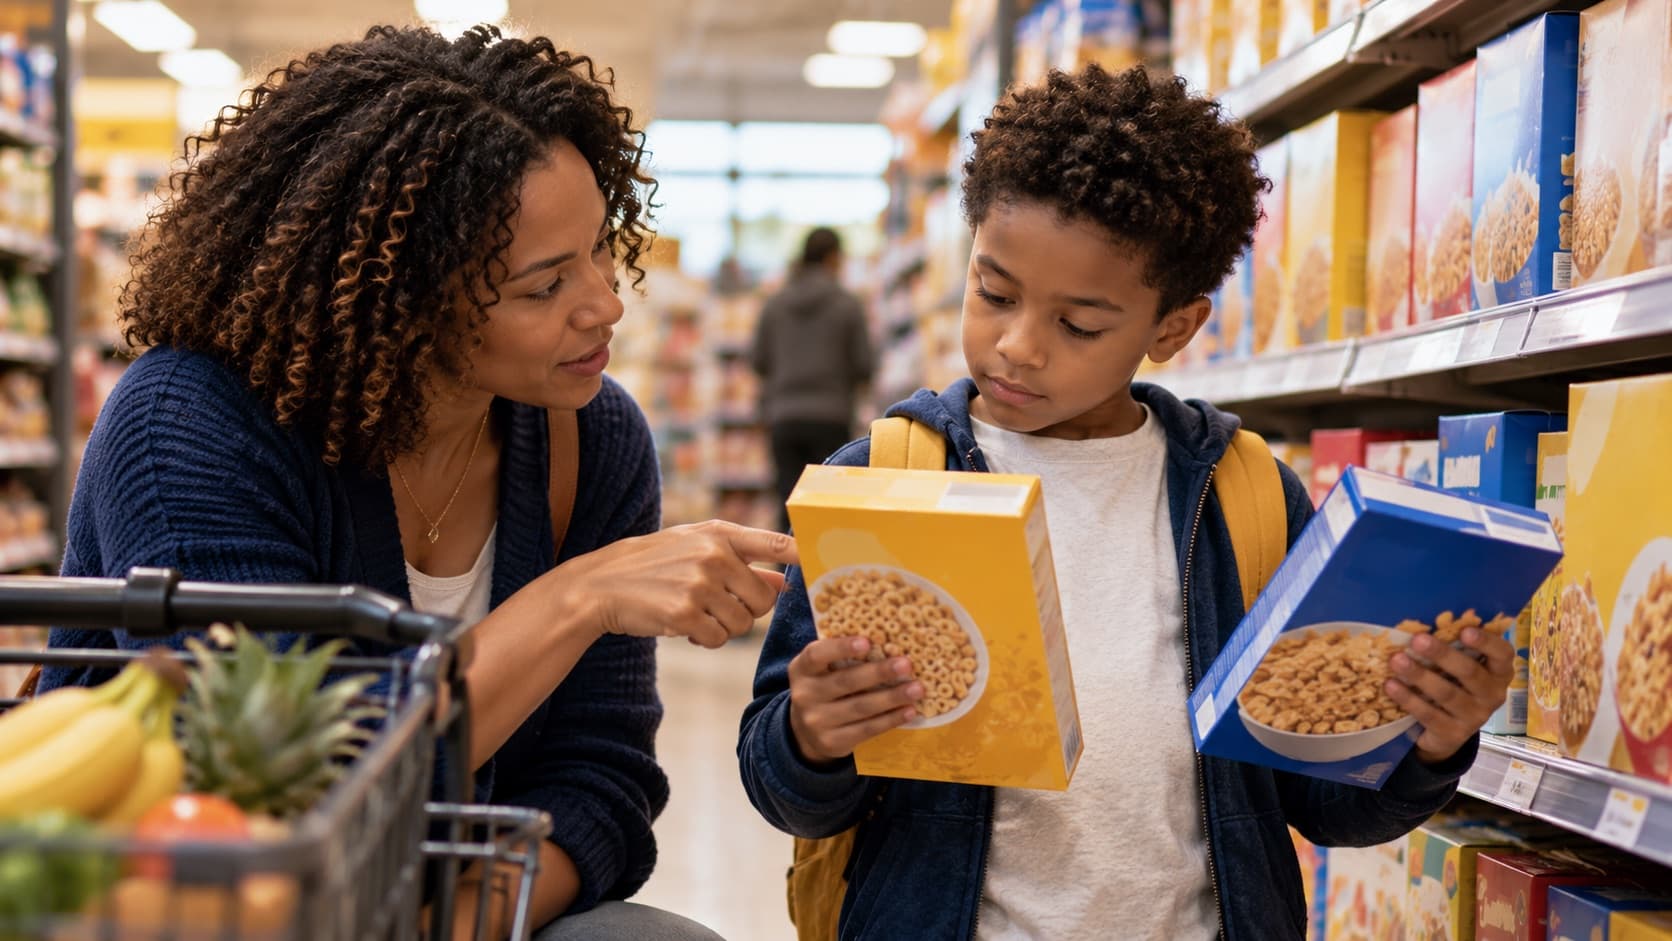
- The store narration. Next time you shop, think out loud: why this brand, why not that one, what you're skipping this week. Children learn more from watching real decisions than from being told rules.
- The waiting shelf. When your child wants something, write it down with the date. If they still want it in a week, it was a real want. If not, they just learned something about impulse.
- Three jars. Spend, save and give. Let the child decide the split and live with it for a month.
- Price the outing. Before a trip or a movie, have them add up what it will cost. Then check afterwards how close they got.
- Print one worksheet. Our free financial literacy worksheets take 20 to 30 minutes and come with answers and a question to ask afterwards.
- Make it a weekly habit. The Family Table™ sets out one ten-minute activity a week, in two versions by age, with the steps and the question to ask.
Financial literacy books for kids
Picture books do something worksheets can't: they let a child feel a money decision before they make one. These four are widely available at public libraries.
Bunny Money
Rosemary Wells · Ages 3–7
Max and Ruby spend a birthday budget one choice at a time. A gentle first look at money running out.
Alexander, Who Used to Be Rich Last Sunday
Judith Viorst · Ages 5–9
A dollar disappears a few cents at a time. Kids see themselves in it, which is the point.
A Chair for My Mother
Vera B. Williams · Ages 4–8
A family saves coins in a jar for something they really need. Saving as a shared goal.
The Berenstain Bears' Trouble with Money
Stan and Jan Berenstain · Ages 4–8
Earning, spending and saving, in a family most children already know.
Money games and apps for kids
The best money games put real choices in front of a child and let the consequences land. The $100 Week™ is ours, and it's free: a five-day browser game where a student gets a starting balance scaled to their age ($20, $50 or $100) and a week of decisions, with no account, no login and nothing collected about your child. For older students, our compound interest calculator and savings goal planner turn abstract ideas into numbers they can change.
When you pick any money app, check three things: that it asks for real decisions rather than quiz answers, that it doesn't collect your child's personal information, and that it doesn't sell anything inside the game.